guess it’s time to start planning my great-grandkids’ mortgage payments now. gotta secure that intergenerational debt early.
A mortgage that lasts longer than your career is how you build generational debt.
Subprime Rides Again, baby.
deleted by creator
At least cars are considered a valid housing choice these days, which is why car prices are rising.
So that’s why PC cases have gotten so expensive.
Honestly, I thought it is actually not allowed in a lot of states to live in your car.
Like stocks, and art, they’re only as valuable as what people will pay for them.
If you want a shelter, you can use sticks and leaves in the forest and build something halfway decent at least. If you want a building to call your home, pay up dickhead.
Meanwhile, people who should be buying are renting, people who should be renting are in airbnbs or living in their cars, and the family dwellings are owned either by some jerkwad who wanted an income property, or a corporation that just felt like owning more land because they could.
I’m so proud of our society. Such progress! Capitalism is great!
If you want a shelter, you can use sticks and leaves in the forest and build something halfway decent at least.
Wrong, someone owns the forest and your encampment will be destroyed upon discovery.
Neat, go build another one down the river.
This is one of the dumbest takes imaginable
deleted by creator
Yeah, the market only cares about the maximum that people will pay for it. You’re not offering the maximum, so you’re not important enough for the market forces to care about.
I’m not either, so… We’re in this boat together. You want to row on the starboard side? Or port?
deleted by creator
As long as we don’t end up going over the waterfall, that should be fine.
I’m feeling we’ll end up going over it whether we row or not.
Anybody who believes a 50 year mortgage is a good idea, does not understand discount rates…
Discount rates are one of my favorite things. But pretend I’m one of those dumbasses who didn’t do the reading…? What would you say to really put those fuckers in their place!?
The further in the future profits are, the less they are worth today. As in getting $1000 today is better, then getting a promise of being paid $1000 in a decade. After all if you got the $1000 today you could have invested it and got a return on it. So lets say you know you can get a return of a rate of 5%. The $1000 today invested over a decade would be $1000 * 1.0510 = $1628.89 in a decade. You can also use it the other way around, to estimate what the $1000 is worth in the future. As in X * 1.0510 = $1000 -> X =$613.91 That rate of return is called the discount rate.
The issue with getting money in 50 years is that it ends up being nearly nothing today. So it is just a horrible idea.
But we’re not talking about getting money in the future. We’re talking about getting full ownership of a house in the future, while being able to live in it for the full 50 years that it is being paid off.
The bank also isn’t talking about getting money in the future, they’re getting a steady revenue stream for 50 years.
So, I don’t see how this really applies to 50 year mortgages.
Headline: Save 200 dollars a month with a 50 year mortgage over a 30 year!
Subtext: … and end up paying double the interest to us for the benefit, and die before your loan is paid off so we get to take the house back from your corpse, sell it on the cheap to a corporate real-estate investment firm (that we have stock in) for just enough to cover the remaining mortgage balance. They’ll turn your multi-generational family home into a shitty rental property or leave it empty to keep the rest of their rents high and your children get nothing cuz fuck em!
So I did the math. A 30 year fixed and a 50 year fixed have a monthly payment difference of $1.
What the absolute fuck.
What?
Some random numbers that are of course VERY variable, but I just ran the calcs with 400k, 5% down, 6% APR for 30 and 50 years
$2648 for 30 years $2369 for 50
Now that is of course not a great deal, presumably you’d also get a little better rate for the longer loan (more points) but it’s not a dollar.
I just question if the 50 is getting the same rate as the 30. Obviously, all else equal, math is math. Banks see that $300 savings as a potential extra $150 a month.
This raises questions about the opportunity cost of $300/mo. It’s not a huge amount of money, but for some budgets, it might make a car payment or groceries possible. Or, if saved or invested wisely, would it tip things in favor of the 50-year term?
$300/month (at the beginning of the month) invested over 30 years, compounded annually at 6% = $198,290.40
If you kept that going for a full 50 years, the last 20 years of interest really starts to ramp up and gives you a final value of $1,084,402.22
If instead, you ONLY paid the mortgage for 30 years, then invest the full mortgage payment of $2,648 into the investment account for the next 20 years (a total of 50 years out. Same end point) you would have an investment account worth $1,215,042.49
So, even in your scenario it is still a loss to take a 50 year over the 30 year, and the 300$ difference is negligible. If $300 was the difference of someone being able to afford groceries or not for the month, then they should not have qualified for a $2,648/mo mortgage.
Don’t forget that on top of all of that you have to pay property taxes.
The calc I used for that number put $3k property tax annually amortized, good call
$3k is generous. We’re paying $12k
Yeah I compared some numbers and guessed a plausible interest rate for the 50 year based on the 15 vs 30 year interest rates at a couple of real banks near me
50 years at 6% with 5% down on 200k (fairly plausible for a decent home where I live and realistic for a first time home buyer who 50 year mortgages are clearly catering to) is 1k/mo almost exactly
- 30 years at 5.85% is 1,121/mo
- 20 years at 5.75% is 1,334/mo
- 15 years at 5.50% is 1,553/mo
So the difference is pretty small on a realistic first time home buyer’s home, but having been on the edge of approval for a home loan before that $100/month can absolutely be the difference between getting the home now and having to wait another 2-4 years depending on markets. In my case they assumed my insurance would cost more and that actually made all of the difference in my home loan application because that shaved about $100 per month off
One interesting side note, one of the local credit unions I looked at offers different interest rates depending on the value of the loan! For a 30 year fixed loan they offer the following rates:
- 800k or less: 6%
- 300k or less: 5.875%
- 200k or less: 5.875% (the APR is lower for this one so presumably the origination fees are lower)
- 100k or less: 5.75%
So yeah that’s new! I’ve not seen that before!
So that’s a great picture I think for the difference between the loan durations.
I of course think the real problem is that average people might need a 50 year loan to barely pay for a house these days. But it isn’t “nothing” between the terms, it does help in the super short term
Because for the first lot of years you are paying basically 0 principal
I owned my first house for 19 years, which was purchased in the fall of 2006. We sold it for the exact same price as we paid for it, and barely came out ahead. I know it was poor timing, but the idea of leaving a home and using it as part of your retirement income is a lie. The banks are laughing all the way to the bank.
Poor timing? You bought at the absolute peak of something known as The United States Housing Bubble. Your experience is not typical. You’re one of the unlucky people who had the absolute worst timing possible.
The idea of using a home as part of your retirement should be a lie, but unfortunately for the vast majority of people it isn’t. The world would be much better off if people only got what they paid back when they sold their houses. But, the reality is that most people have been absurdly lucky and their homes have been going up faster than all but the best stocks on the stock market. You just happened to be someone who jumped on the ride at exactly the wrong time.
I don’t disagree with any of your points.
Median home prices peaked at $216,000 in August 2006. The lowest they’ve been in 2025 is $414,000. You had some absolutely atrocious luck. You buy in Detroit or something?
Not who you responded to but it depends entirely on the location. In the northeast there is decent and consistent appreciation and there has been for decades because it has always been populated. But home appreciation over 20, 30, or 50 years will struggle to beat the S&P500. Factor in property taxes and upkeep and you may just barely keep up with inflation. Just from inflation $216k in 06 would be $358k in 2025. As an asset its primary function is being a store of wealth that happens to be the roof on your head, something you can refinance to borrow money, and something to sell basically to pay for whatever you downgrade to when you enter the stage of preparing for death, whether it’s a condo or a nursing home.
All the money to be made comes from buying in bulk and renting out to people who cannot afford because everyone bought to rent out, while local government restricts supply through zoning because it would lower property values of everyone who only had their house as retirement because wages have not kept up with productivity or inflation and pensions and unions have been gutted.
You’re right, but he did say the monthly payment was the difference, not the interest payments. That typically doesn’t change throughout the life of the loan. I wonder what the math formula looks like for a 50 year fixed?
With this math I just acquired a 10 year fixed for $1 more per month.
Why would anyone take one out in that case then? You can always overpay and pay it off sooner though.
I’ll counter with a 100 year 2% mortgage
I’m pretty sure interest only mortgages already exist in some places.
Isn’t that just renting?
Almost, it’s just now you also have to pay for renovations and stuff yourself.
Cool. Put it on my credit card.
You do get to keep any growth in the value of the property too
Or eat any loss in the value of the property
define “keep” if you cant ever put your name on it
I’m gonna be dead in 20 years, so I’m so sorry to have to turn this down lol
They’re considering offering a 50-year mortgage product to a market where the average first time buyer age is 40. Like no joke they’re aiming to lock people into a mortgage that would cost more per month than renting the same property until they’re 90.
they’re aiming to lock people into a mortgage that would cost more per month than renting the same property until they’re 90.
How do you figure that?
Rents are already higher than mortgages and the whole point of the 50 year mortgage is a lower monthly payment, but okay yeah I’m the idiot.
Me too bro, me too.
I’ll take a 90% 1,000 year loan please.
(hint: it would be over $30,000 per month payment)
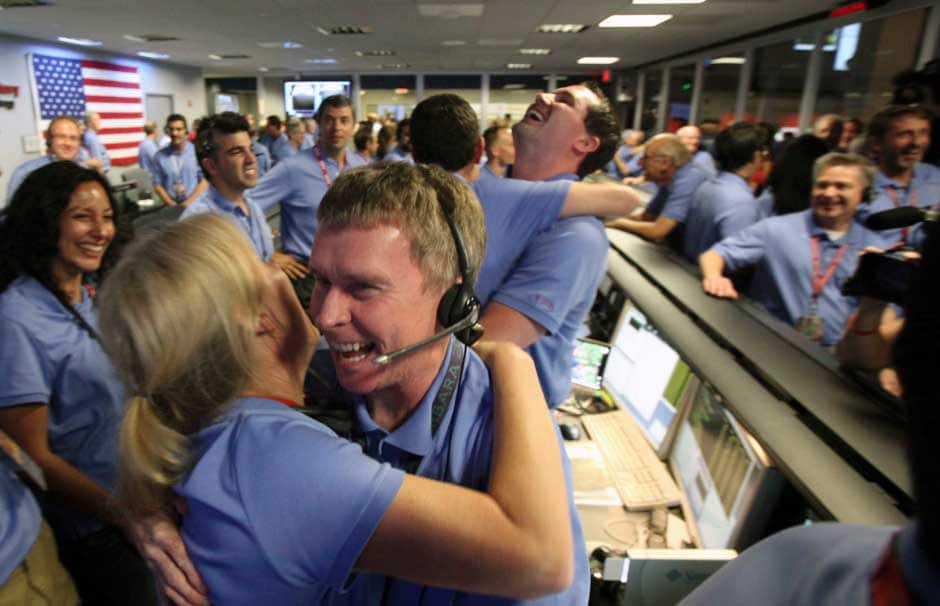
Why does he suddenly have vampire teeth
Probably because it’s a cropped section of a shitty AI upres of a video still, here’s an original.
It’s from 2012 when the NASA JPL team did a successful first-ever “rocket crane” landing to get the Curiosity rover onto the surface of Mars. It was actually a really touching / exciting moment, there’s lot of other photos out there of the team hugging and celebrating.
A 50 year mortgage will be a lot like renting. Because the bank will own your shit until you die.
That’s what we get for saying “why can’t I get a mortgage when I pay more in rent just bc my credit is bad”, the banks figured out how to rent properties to you.
Average age of a first time homebuyer is now over 40. Even at a reasonable interest rate, most buyers would die before they actually own the house.
And then their kids keep paying until they die and still haven’t paid it off, even though they’ll have paid twice the original amount by that point. Whoever came up with this bullshit is probably right now buying their third yacht from the bonus.
30 year mortgage means you pay for the house twice with interest. 50 year mortgage means paying for the house 3x.
As intended
Can’t pass it on to your kids when the bank forcloses on it
Were not enough boomers taking them up in reverse mortgages?
Because that’s where all my “generational” wealth went. “We can’t take it with us Jimmy” though we did, in fact, take it from those who came before.
I know someone living in the Netherlands (home of Lemmy.world!) that told me they had interest only mortgages that didn’t pay toward the principal and that this was common over there. It seems like these new 50 year mortgages in the USA are a step going that same way. Anyone from that area confirm this?
I’m Dutch, just bought a home, and I’ve never heard of that.
Edit: I think that is called an “afloasingsvrije” mortage, banks stopped providing those after 2008 for obvious reasons.
Eidt 2: Apparently it still exists, but can no longer be used to finance an entire house. From my research it is often still possible for up to 50% of a house’s value. It was also not an option in the way we bought our house.
In the UK they were popular for “buy-to-let” properties - so it didn’t really matter that you have barely any equity in your second home, so long as the rental income covers the interest payments.
Congratulations on your new home!
Thanks for providing that info on the “afloasingsvrije” mortgages. It was a few years before 2008 when she bought, so that tracks with what you’re reporting.
Here in the USA we have fixed rate mortgages, where you have a single fixed interest rate for the entire length of the mortgage, but I know that not all countries have that. From what I understand in Canada the rates fluctuate during the mortgage where you can get something like fixed for 5 years (maybe 10?) but then the rate can increase on the existing mortgage you’ve already got.
How does the Dutch system work? Fixed for life of mortgage? Continuously variable? Fixed for a time like Canada? Something else?
We have different types of mortages, but most (maybe all, at least the most common types) have a fixed rate over 30 years. Maybe variable rates exist, but they are at least very uncommon. Shorter mortages are also possible I think but are of course very expensive.
One weird thing we have is that part of the interest you pay is tax deductible. (Progressive parties are i.m.o. rightfully trying to abolish this subsidy for the owning class, but I digress.) for this reason there is a type of mortage where you first only pay the interest, and slowly start paying off more and more of the mortage, which means your net mortage fee slowly increases over time, which is nice if you expect your income to increase over those decades.
One weird thing we have is that part of the interest you pay is tax deductible.
This matches the USA system for mortgages.
for this reason there is a type of mortage where you first only pay the interest, and slowly start paying off more and more of the mortage, which means your net mortage fee slowly increases over time, which is nice if you expect your income to increase over those decades.
This sounds new to me. In the USA we do have amortized mortgages so a very high percentage of the monthly payment is interest with little going to principal. Over time that relationship flips where you’re paying more principal that interest. However, in our system the mortgage payment stays the same, only how much of that fixed payment goes to interest vs principal changes.
Oh yeah the gross mortage payment stays the same. But over tme less of it is tax deuctible. Sounds like that system is the same across the countries.
Screw .world
you…realize thats not only where this Lemmy Community is…but also your user account, right?
Yep.
Nothing is stopping you from moving to another Lemmy server and blocking .world entirely. You have to find some value here if you haven’t done that already. If you hate it so much why are you still here and posting instead of on another server with other non-Lemmy.world communities?
Because I’m lazy
How would that work, even on paper? Not being a dick, just don’t understand. So it’s literally just, “you can never own this property fully?”
UK has even worse, buy to let. Interest only with the intent of renting it out. So you profit on the rents and profit on the house going up in value. Obviously you vote for governments that will lead to an increase in house prices too. Oh yeah most of government is made up of
parasiteslandlords too.Sorry, my brain is struggling. How is this different from the U.S., for example? Isn’t it the same? If you buy, the only way to make money is to improve or rent out to someone even more desperate…?
Normally you also make payments towards the principal and build equity. As I understand, most of these buy to let loans actually only have you pay interest so you’ll never own the property. If the value even after 20 or 30 years drops below the initial value, you’re in the negative and need to pay up the difference if you can’t make payments anymore. Whereas with a normal mortgage once you’ve paid it off, fluctuating values can’t put you in severe financial trouble.
How would that work, even on paper? Not being a dick, just don’t understand. So it’s literally just, “you can never own this property fully?”
Yes. The tradeoff is you have a property that is in your name (with a bank note attached), and if the property increases in value during the time you own it, when you sell, you pocket the difference. If you have a fixed interest rate, it also caps the growth of your payment for housing for the entire time you live there. There’s quite a bit of value in that.
At that point, the bank is buying the house, they’re just renting it to you for a very cheap rate, with the stipulation that you’re responsible for all of the maintenance and etc. The “purchase” is just you entering into a long-term rental agreement.
There is still some optionality like maybe you get a windfall from a boomer dying and you can pay the principal. Or in 30 years your currency devalues to the point you can afford the principal.
Anyway it all feels like fool’s hope. Situation is fucked.
Without the benefit of renting. Hell don’t forget home insurance.
It an overall bad deal in my mind, but there are some upsides (not enough for me to take it). Assuming you get a fixed rate, you lock in your payment and your “rent”/mortgage will decline over time just from inflation eating away at it. I think most folks would love to have their rent decline by 3% every year. This effectively does that.
Additionally, if you are the homeowner instead of the renter, if the real estate increases in value, when you sell, you pocket the increase. There’s nothing like that in renting.
Not sure if this is what they were talking about, but balloon mortgages are a thing here too. I can’t ever imagine considering one, but they exist.
Balloon mortgages would be good in only two situations:
- you’re not planning on living in the house very long, so you likely exit before the balloon payments hit.
- you believe interest rates will decline in the next few years and you can refinance to a fixed low rate
I don’t ever see myself using a Balloon mortgage. Worse, they are frequently sold via predetory lending methods. Unsavvy buyers are convinced to take a balloon mortgage not understanding the payments will rise dramatically in the years ahead. This can lead to eventual foreclosure when the owners can service the higher payments.
If you’re not planning to live there long, I don’t think you shouldn’t be buying; that’s one of the few times I’d choose to rent. I guess maybe if home prices are rising then you can accrue some equity, but then you risk buying at the top of the market. I genuinely how it would compare to a fixed rate mortgage though.
If you think interest rates are going to decline, you can easily refinance a fixed rate mortgage as well. I don’t see any benefit in that scenario, but there’s a downside in that if rates don’t go down you still have that balloon payment to worry about, and if you don’t qualify for a traditional mortgage, you’re really in a bind.
Maybe if you’re flipping a house it makes sense, especially if you want to minimize cash outflow. Otherwise, there are so many more downsides that are much more severe than the mild upsides that you might gain. Perhaps there’s a few niche applications that I haven’t considered though.
Dutchie here, nope. We are paying both principal and interest. Plus when i to it out, my mortgage was 102% of my home’s value. And as it stands, the bank owns my ass exactly until I retire 🤷♂️
At least someone wants to pay for your ass. I can’t give this thing away.
I hear ass is pretty easy to give away. Much harder to get ass, especially if you’re choosy about the gender of the ass owner.
Late stage capitalism demands that you will own nothing.
So basically you won’t own shit.
Never did.
The year I turned 40, was the year I moved into my first non-rental property.
I’m living proof that shit is fucked up
I’m turning 40 in a few days. I finally moved into a crazy beat-up fixer-upper/possible crime scene about 3 weeks ago.
Welcome to the club. Were you able to afford the fixer upper on your own, or did you need to split the financial burden with another person?
I found a rare rent-to-own locally. So it’s in my name and otherwise the same as buying, except the original owner is the bank. As long as I stay 2-3 years, I come out ahead if viewed as a rental. If I make it 20 (or can get ahead/clever in various ways), I own it outright/maybe make a little bit.
Good luck.
I’m a couple of years older and JUST escaped renting. It’s ridiculous!
Welcome to the club.
What percentage of your income now goes to your mortgage payment? For me, it’s like 110%… But I have help, so my share is only like 35%
It’ll actually work out better for me since I currently live by myself and pay all the rent and utilities, and I’m buying with my partner so I’ll finally be able to share the load 😀
Such a stupid, stupid society.
Is this an actual thing in the us? We don’t have 50 year mortgages in Denmark but I can get a 30 year fixed interest at 3.5%
No, but our Treasury Secretary recently floated the idea so it might become a thing soon. I believe there are already some 40-year mortgages, but they’re rare and non-standard. The 30-year mortgage has been an American institution since it was standardized under FDR’s New Deal in the 1930s.
Not a thing yet AFAIK, but Trump proposed the idea this week. You can get 30-year ones here in Canada too, but I’m not sure what the lowest fixed interest rate is currently.
trump just announced 50 year mortgages
this is so awesome I can’t wait to be in debt my entire life
Debt slavery is the new black. Indentured servitude is back.
That’s the fun part, you probably were already going to be!
Don’t forget about paying back triple what you borrowed!
and your kids will be in debt.
If mortgages were capped to 20 years, the prices of houses would plummet.
But are they really 17% interest rate?
No. Mortgage interest rates are in the 6’s right now in the US
No, it’s just some exaggeration to make it even more ridiculous. As if 50 years isn’t enough.
What’s really awful is when you see how little the payment lowers between a 30yr and 50yr mortgage with current rates. It’s not nearly as big a difference as you’d think.